‘That’s When You Walk Out:’ Chevrolet Salesman Closes on a Deal at $605 per Month. Then the Finance Department Steps In
"It’s called a bump."
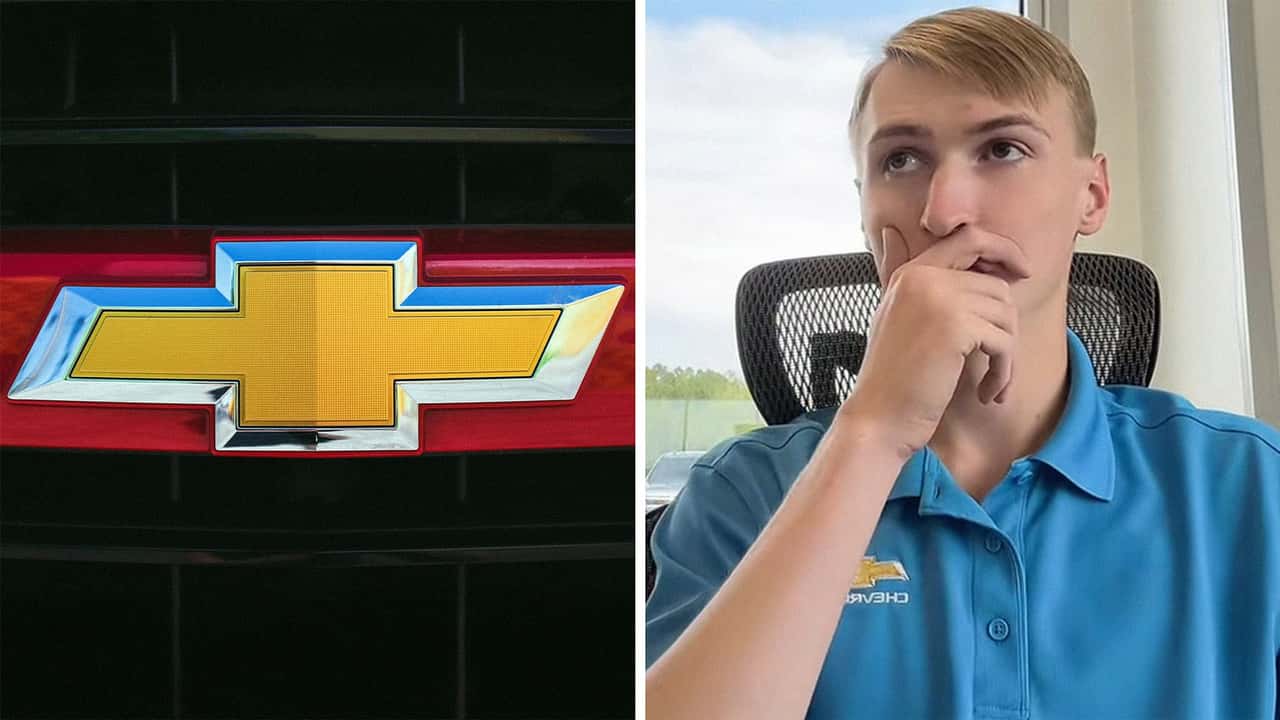

A Chevrolet salesman has highlighted the tension between the finance department and sales in a viral video.
TikTok user Charlie Isard (@charlie.sells.carz) is a Chevrolet salesman based in Michigan. In a video posted on July 19, he shares what happens when the deal he closes doesn’t match the paperwork from the finance department.
"POV: You close the customer at $605 a month and then the finance department changes the payment to $895," reads the on-screen text. Isard sits at his desk as an audio of an irate man plays in the background.

In the caption, Isard explains what might've gone wrong.
"Interest must have come back higher than expected," he writes.
The Dealership Bump
Consumer Reports encourages car buyers to negotiate dealership fees and separates them into two categories: “Legitimate costs” and “fees you should contest.”
Legitimate costs include documentation charges, registration charges, and sales tax. The outlet advises consumers to contest advertising fees, delivery and preparation fees, market adjustment fees, and loan payment fees.
Consumer Reports also warns to look out for unnecessary add-ons such as VIN etching, extended warranties, disability and life insurance, and rustproofing.
How Should You Finance?
Both bank and dealership financing come with pros and cons.
Buyers who are worried about being pressured to spend more at the dealership often opt to secure financing through a bank. That way they’re not shopping first and negotiating a loan second.
People with credit scores on the higher or lower end may benefit from the financial options or promotions dealerships offer exclusively to people who finance through them.
They may also simply want to close a deal quickly even if that convenience comes at a cost. Dealerships’ approval process is typically much quicker than banks'.
On the other hand, Bankrate.com reports that banks, credit unions, and online lenders typically offer lower interest rates than car dealerships.
In the comments section, viewers lamented the realities of making a deal at the car dealership.
"That's the problem with estimating payments," wrote one person. "Unfortunately, you can't assume the rate they will get until you run credit. Most won't even tell you that they have bad credit until then, so they should expect it. Or the [increase] was adding a warranty.
"It's called a bump," wrote a second. "All dealerships do this to get more money. That's when you pull the manager aside and say it was all included, then walk out."
A third user said, "Never finance through a dealership."
Update July 29: In a direct message to Motor1, Isard wrote, "As a customer, if the dealership is hiding the interest rate, you need to leave immediately, because there are plenty of truthful dealers out there that won't do that."
More From Motor1
RECOMMENDED FOR YOU

Man Has Pedal Commander In His Chevrolet. It’s Uninstalled. American Auto Shield Still Denies His Warranty—And Cancels His Policy
Modern Cars Are Packed With Sensors. What Do They All Do?
Cars Keep Hitting Man’s Mailbox. So He Makes It Indestructible. But Could He Be Sued?
BMW's Electric Cars Are Helping Keep Its V8s Alive
Manager Tells Buick Dealership Saleswoman To Sell Encores. Then She Drives 5 Of Them And Realizes None Of Them Work
Used EV Prices Were Plummeting. Now They're More Expensive Than Gas Cars
Mechanic Works On New Hyundai Elantra. Then He Realizes It Has Too Much Break-In Oil: ‘All Of Them Do This’